Buy Before Selling in Phoenix: A Family Move Plan
If your family needs to relocate before your current home sells, buy before selling can work, but it requires a written plan. The right steps can protect your finances and keep the move manageable. Remember, the strategy of buy before selling is often about timing and financial planning.
I’ve helped plenty of families through this, including adult children helping parents make a later-life move. You don’t have to rush into a risky loan or bad offer because the calendar feels loud.
In considering to buy before selling, you must weigh out the financial implications and risk management strategies that come with such a decision. Families who successfully buy before selling often find themselves more in control of their transition.
We’ll cover the decisions that make the next 60 to 180 days more manageable. Confirm your borrowing range and get lender preapproval before touring Phoenix homes.
The option to buy before selling allows families to explore available homes without the pressure of selling their current property first, which can lead to better decision-making.
Key Takeaways
Buy before selling is a strategy that many families consider, ensuring they have a plan in place for both financial and emotional transitions during the move.
-
- Buying before selling can solve real timing problems, but only if your income, equity, cash reserves, and timeline support the overlap.
Understanding when to buy before selling can help families navigate the complexities of real estate transactions in Phoenix.
- Run a 90-day two-house payment test that includes mortgages, taxes, insurance, HOA dues, utilities, repairs, moving costs, and temporary housing.
- Confirm financing directly with your lender before relying on a HELOC, home equity loan, bridge loan, specialty program, or mortgage recast.
- A home sale contingency or rent-back agreement can reduce risk, but the offer terms need to fit the seller’s goals and current Phoenix market conditions.
- Prepare your current home for sale and write down a backup plan in case it takes longer to sell than expected.
When buying first makes sense in Phoenix
Buying first is usually about control. Choosing to buy before you sell or wait for your current home to close depends on your timeline and finances. You want time to find the right house, get the kids settled, or help a parent move without forcing everyone into a rental.
When you buy before selling, it offers more control over your timeline, allowing you to make decisions that suit your family’s needs.
That can be reasonable. It can also get expensive fast.
A new home may solve a real timing problem
A family relocating to Phoenix may need to be here before a school year starts or before a new job begins. A downsizer may need one-level living near doctors, adult children, or longtime friends.
The decision to buy before selling might be essential for families needing to settle quickly due to school schedules or job relocations.
In those cases, waiting to sell can create its own headache. Temporary housing may mean rent, storage costs, and a second move, along with a lot of “Where did we pack the coffee maker?” mornings.
Buying first can be a good fit when you have strong home equity, solid cash reserves, and realistic net proceeds from the old home.
Selling first can protect your budget
Here’s what most people don’t realize. Your home equity isn’t cash until the home sells, or until a lender approves a way to borrow against it.
Whenever you buy before selling, you must also assess your financial safety nets to avoid overextending yourself.
If your current home has a mortgage, buying first can leave you with dual mortgages. The risk includes more than principal and interest. Add property taxes, insurance, HOA dues, utilities, pool care, and repairs. That overlap is where people get stuck.
The cleanest financial plan is often to sell first, but it may not fit school, employment, caregiving, or accessibility deadlines. The right answer depends on your timeline and your tolerance for carrying costs.
Run the two-house payment test before shopping
Don’t start with the question, “How much house can I buy?” Start with, “What happens if my old house takes longer to sell than expected?”
I want families to run this test before shopping, then obtain or update their preapproval. A preliminary online estimate isn’t approval.
Families looking to buy before selling should also consider how market conditions might impact their choices.
Count every monthly cost
Your mortgage lender will review income, debts, credit, assets, and your debt-to-income ratio. Ask how your debt-to-income ratio changes if both housing payments count. Get a scenario-specific underwriting answer before writing an offer.
The Consumer Financial Protection Bureau’s Ability-to-Repay guidance explains why lenders look beyond the purchase price. They need to see that the payment works with your verified finances.
Build your test around these costs, including the proposed down payment, and confirm your emergency fund remains untouched.
- The current mortgage, including taxes and insurance.
- The projected new mortgage, taxes, insurance, and HOA dues.
- Minimum payments on any HELOC, bridge loan, or home equity loan.
- Utilities, upkeep, and likely repairs for both homes.
- Moving expenses, storage, travel, temporary lodging, and utility setup.
Give the old house a longer runway
Those who buy before selling often need to plan for additional costs that may arise during the transition period.
I like a 90-day overlap test, but it’s a planning standard, not a guarantee. If your old home sold tomorrow, great. But could you make the plan work if it took three months?
A “we’ll list it next week” plan is not a backup plan. A backup plan is the cash and housing plan that still works if the old home needs time.
Don’t base your down payment on the highest number you hope to get. Estimate realistic net proceeds after the existing mortgage payoff, commissions, seller concessions, repairs, and closing costs. That figure shows the usable home equity available for the next purchase.
Financing options for buying before selling
Evaluating your options to buy before selling can lead to a smoother transition and less stress during the moving process.
There is no magic financing product when you buy before selling. Every option shifts the risk somewhere else. The financing method affects more than the advertised purchase price, so know where the risk lands before you sign.
A HELOC can create flexibility
A home equity line of credit, or HELOC, lets you borrow against available equity in your current home. The CFPB’s explanation of a HELOC describes it as open-end credit, meaning you can borrow, repay, and borrow again during its draw period.
Utilizing a HELOC can be a smart way to buy before selling, allowing access to equity without waiting for your old home to sell.
For a move, it can provide part of the down payment before the old house sells. The full cash requirement also includes reserves and prepaid items.
Here’s the trade-off. The HELOC is secured by your current home. Variable interest rates can change, payments can shift, and the lender may re-check your finances or property value. Don’t assume a line you discussed six months ago will still be available on closing day.
A fixed home equity loan gives you a lump sum and a fixed payment. That can feel more predictable, but interest begins on the full amount immediately.
A cash-out refinance may change the existing loan, rate, payment, or closing costs, affecting the full cash requirement. That cash-out refinance may not be practical when the move is time-sensitive, and it isn’t automatically better than a line of credit.
A bridge loan or specialty program costs more than convenience
A bridge loan is short-term money meant to cover the timing gap between two homes. It can help you make a stronger offer because you aren’t waiting for sale proceeds.
A bridge loan is another option for those looking to buy before selling; however, it often comes with higher costs.
The risk is plain English. You may owe the bridge loan, your old mortgage, and your new mortgage until the first property sells.
Specialty purchase programs may help buyers write non-contingent offers or provide temporary purchase funds. Read every fee sheet. Ask about program fees, deadlines, sale or listing requirements, repair rules, and what happens if your home doesn’t sell by the required date.
When considering specialty programs, confirm how they can help you buy before selling without overwhelming your budget.
| Option | Where the money comes from | Main trade-off |
|---|---|---|
| HELOC | Equity in your present home | Variable rate and a lien against the old home |
| Home equity loan | Equity in your present home | Fixed payment begins right away |
| Bridge financing | Short-term lender financing | Higher carrying costs if the sale is delayed |
| Specialty purchase program | Provider financing and program structure | Fees, timelines, and rules can be restrictive |
| Sell first with rent-back | Sale proceeds | You need a buyer willing to let you stay after closing |
Confirm availability, underwriting, payoff timing, and qualification directly with the mortgage lender before relying on any option.
A mortgage recast can help after your old home sells. You make a large principal payment on the new mortgage, and the lender recalculates a lower monthly payment using the same rate and remaining term. It isn’t automatic, and not every loan qualifies. Ask before you depend on it.
For a fuller look at variable-rate risks and terms, the CFPB’s HELOC consumer booklet is worth reading before you borrow.
Make the purchase offer fit the situation
The financing is only half the story. Your offer has to make sense to the seller, too.
A home sale contingency protects you, but it can weaken the offer
A home sale contingency says you’ll buy the new home only if your current one sells. It protects you from carrying two homes longer than planned.
The importance of evaluating your timing when you buy before selling cannot be overstated.
Market conditions and seller goals affect the response. In a sellers market, a seller may favor a cleaner offer. In a buyers market, the same protection may be easier to accept. Even in a sellers market, the response can vary by Phoenix submarket, property, and timing.
That doesn’t mean contingencies are bad. It means the home sale contingency needs support from the rest of the offer. Price, earnest money, inspection terms, timing, and documentation can make it more acceptable to the seller.
Before writing an offer, have a current preapproval letter, proof of funds, and a clear sale timeline ready. Your real estate agent can help coordinate the offer terms, seller communication, and timing.
I often tell buyers to prepare their existing home before they shop. Finish small repairs, declutter, arrange photos, get a pricing analysis, and write a clear timing plan. Review whether the home is realistically positioned, rather than assuming an optimistic listing price will produce the proceeds you need. If the right Phoenix home pops up, you don’t want your own house to be the loose shoelace.
A rent-back agreement can remove one moving day
A rent-back agreement lets you stay in your sold home for a defined period after closing. It can give you time to close on the replacement home, pack properly, and avoid moving twice.
A clear understanding of the process when you buy before selling helps manage expectations.
Put everything in writing: daily rent, deposit, insurance, possession date, damage responsibility, and the post-closing occupancy limit. Once the home closes, it isn’t your house anymore. That changes the conversation.
Phoenix neighborhoods change the timing equation
Phoenix is not one market. The Phoenix-Mesa housing data tracked by FRED provides metro context, but a broad number can’t price or time an individual property in the local real estate market.
The broader housing market can look different from one ZIP code to another. Condition, location, lot size, price range, and buyer competition matter more when comparing nearby homes.
Market conditions can shift inspection leverage and offer timing. When buyers have more leverage, a sale-related contingency may be easier to request. When sellers have more leverage, you may need stronger terms and a faster offer. Conditions vary by ZIP code and price band.
Match the house to the daily routine
For relocating families, I keep the first conversation practical. Where will you drive on a Tuesday morning? Where are the schools, doctors, grocery stores, and people you actually need nearby?
The Sheaborhood in 85028 can suit families seeking mountain access, established streets, and room for family life. Older homes are common, so roof age, HVAC age, windows, and pool equipment deserve a hard look. A low list price can become expensive after inspections.
If you’re bringing grandparents closer, read my guide to Phoenix neighborhoods for multigenerational families. Proximity changes the whole rhythm of a family move.
Don’t treat every ZIP code the same
Areas with higher competition may challenge your ability to buy before selling without taking higher risks.
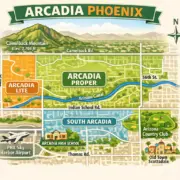
Arcadia and Biltmore can have higher entry points and sharper buyer expectations. North Central Phoenix, 85020, 85032, and 85254 offer different home ages, lot sizes, and commuting patterns.
In 85021 and 85028, one-level ranch homes can be especially appealing to downsizers. They aren’t always turnkey, so budget for inspection findings before deciding how much equity can go toward the new purchase.
Downsizing without turning the move into a crisis
When a parent is moving, the house isn’t always the hardest part. Possessions, routines, and emotions can weigh more than the loan paperwork.
I’ve helped many adult children through this exact situation. The best moves give everyone room to make decisions without making every item feel urgent.
Choose the next home before clearing the old one
A smaller home needs a plan for furniture, storage, hobbies, guests, and mobility. Don’t assume downsizing means choosing a condo. Some people want a one-level patio home, while others prefer a smaller house with a yard and a familiar neighborhood feel.
The Sheaborhood offers several possibilities, including smaller single-family homes, patio homes, and condos near Stone Creek. Compare each option based on daily routines, accessibility, storage, and long-term comfort.
By considering the pros and cons of buy before selling, families can make informed decisions that align with their needs.
Keep a temporary housing option in reserve
Sometimes choosing to sell first is the calmer move for a senior household. It can protect cash flow and reduce pressure to make a rushed purchase.
A furnished rental, family guest room, or short rent-back can provide temporary housing while the family evaluates its options. Nobody wants to move twice, but moving expenses for storage, movers, accessibility changes, and duplicate trips may cost less than buying the wrong home.
Frequently Asked Questions
Addressing common questions about how to buy before selling can aid families in their planning process.
Is buying before selling a good idea?
It can be a good fit when you have strong equity, stable finances, cash reserves, and a clear reason to move before your current home sells. The decision becomes riskier when carrying two homes would stretch your budget or emergency fund.
How long should I plan to carry two homes?
Use a 90-day overlap test as a planning standard, not a guarantee. Include both housing payments, taxes, insurance, HOA dues, utilities, upkeep, repairs, moving costs, storage, and temporary lodging.
Can I use a HELOC to buy a home before selling?
A HELOC can provide access to your current home’s equity for part of the down payment or cash requirement. It also creates a lien against the old home, and variable rates, changing payments, and lender approval requirements can add risk.
What is a home sale contingency?
A home sale contingency makes the purchase dependent on selling your current home. It can protect you from carrying two homes, but it may make your offer less competitive, especially when sellers have more leverage.
What should I do if my current home does not sell on schedule?
Decide in advance whether you would reduce the new-home budget, accept a rent-back, rent temporarily, or keep more cash untouched. Review that fallback plan with your lender, real estate agent, and family before making an offer.
A backup plan keeps everyone calmer
Before making an offer, run a 90-day two-house budget test and confirm financing with your lender. Prepare the current home for sale, then choose offer protections that match your timeline.
Write down what happens if the old home doesn’t sell on schedule. Review the plan with your lender, agent, and family before making an offer.
Your fallback might mean reducing the new-home budget, accepting a rent-back, renting for a few months, or keeping more cash untouched. None of those choices are failures.
Ultimately, the goal of buy before selling is to create a smoother transition for your family during stressful times.
The point of buy before selling is to create breathing room, not force a perfect timeline. A clear plan helps your family make a smart move with fewer surprises.